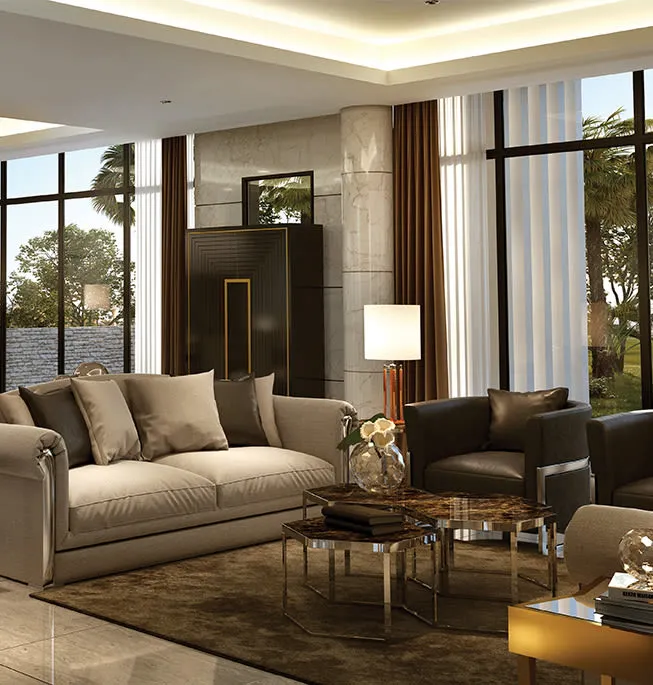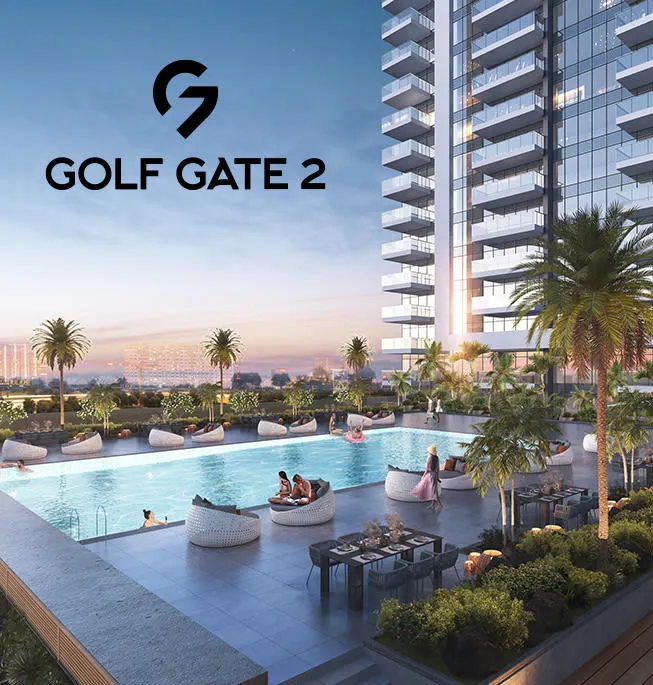
DAMAC Lagoons District, Valencia
DAMAC Lagoons
- Studio to 2-bedroom apartments
- Apartments
- Handover Q3 2029
DAMAC Properties
View project
Dubai property guide
60 projects documented
DAMAC Lagoons
DAMAC Islands, Dubailand
Dubai Canal
Al Wasl, Sheikh Zayed Road
Dubai Harbour
Dubai Maritime City
Al Sufouh
Al Safa, Dubai Canal
DAMAC Hills
DAMAC Hills
DAMAC Hills
DAMAC Hills
DAMAC Hills
The final 30 per cent is due on handover, when the property is registered in your name.
Each instalment is usually linked to a construction milestone, such as the foundation, the structure or the finishing works.
Because most of the amount is paid before handover, the 70/30 plan leaves less to arrange at the end. That matters if you are buying with cash and want the handover payment to be small, or if you want to keep your mortgage borrowing low at handover.
That adds up to 70 per cent during the build. The remaining 30 per cent is paid on handover.
Real schedules vary between developers. Some ask for a lower booking payment and more instalments after that. Some tie instalments to fixed dates rather than construction stages. A fixed-date plan keeps asking for money on schedule even if the building is behind, so a construction-linked plan is easier to follow. Check which type your plan is before you sign.
The plan suits buyers with strong cash flow during construction. If your income is steady and you can meet larger instalments while the building goes up, the smaller final payment makes handover easier. It suits buyers who want to keep the amount they borrow at handover low, and buyers who prefer to have most of the purchase settled before they take the keys.
It suits end users who are buying a home to live in and who have savings set aside for the build period. It also suits buyers who do not want to rely on a mortgage for a large final payment, because the 30 per cent balance is easier to cover from savings or from the sale of another property.
It is less suited to buyers whose cash flow is tight during construction. If the instalments are a stretch, a 60/40 plan asks for less during the build, and a post-handover plan spreads part of the amount over the years after handover. Match the plan to what you can pay each time an instalment falls due, not to the headline split.
The difference is timing. Under 60/40 you pay 60 per cent during construction and 40 per cent on handover. The total amount is the same. What changes is how much you pay before you get the keys and how much is left to find on the handover date.
Choose 70/30 if you can pay more during construction and want a smaller balance at handover. Choose 60/40 if you want lower instalments during the build and you are comfortable arranging the larger final payment, often with a mortgage. Neither plan is cheaper in itself: the total amount is the same, and the choice is about cash flow.
Some developers offer the same project on both plans, with the 70/30 version carrying a small incentive, such as a lower booking payment or the transfer fee covered. Compare the full terms, including the instalment dates and the incentives, before you decide. An incentive is only worth having if it is written into the SPA.
A post-handover plan keeps part of the amount payable after you receive the keys, usually over one to three years. It is the opposite of the 70/30 approach: instead of paying more before handover, you pay less and finish paying after you move in or rent the home out. Post-handover plans suit buyers who want rental income to help cover the remaining instalments.
The 70/30 plan suits buyers who want the purchase mostly settled by handover and who do not want to owe money after they move in. If you prefer to be clear of payments when you take the keys, 70/30 is the better fit. If you prefer lower payments during construction and after handover, a post-handover plan is the better fit.
Check the handover date, the delay clause, and whether the plan is transferable if you need to sell before handover.
Check the costs outside the plan: the Dubai Land Department transfer fee, normally 4 per cent, the registration fee, the agency fee and, if you borrow, the mortgage arrangement fee. Some developers offer to cover the transfer fee, but check whether the offer is in the SPA and what it excludes.
You pay 70 per cent of the amount during construction and 30 per cent on handover. It leaves a smaller balance to find when you receive the keys.
It depends on your cash flow. 70/30 asks for more during construction and less at handover. 60/40 asks for less during construction and more at handover. The total amount is the same.
Yes, normally for the 30 per cent due on handover.
Ask about the resale rule and any fee before you buy.
No.